What is Garner?
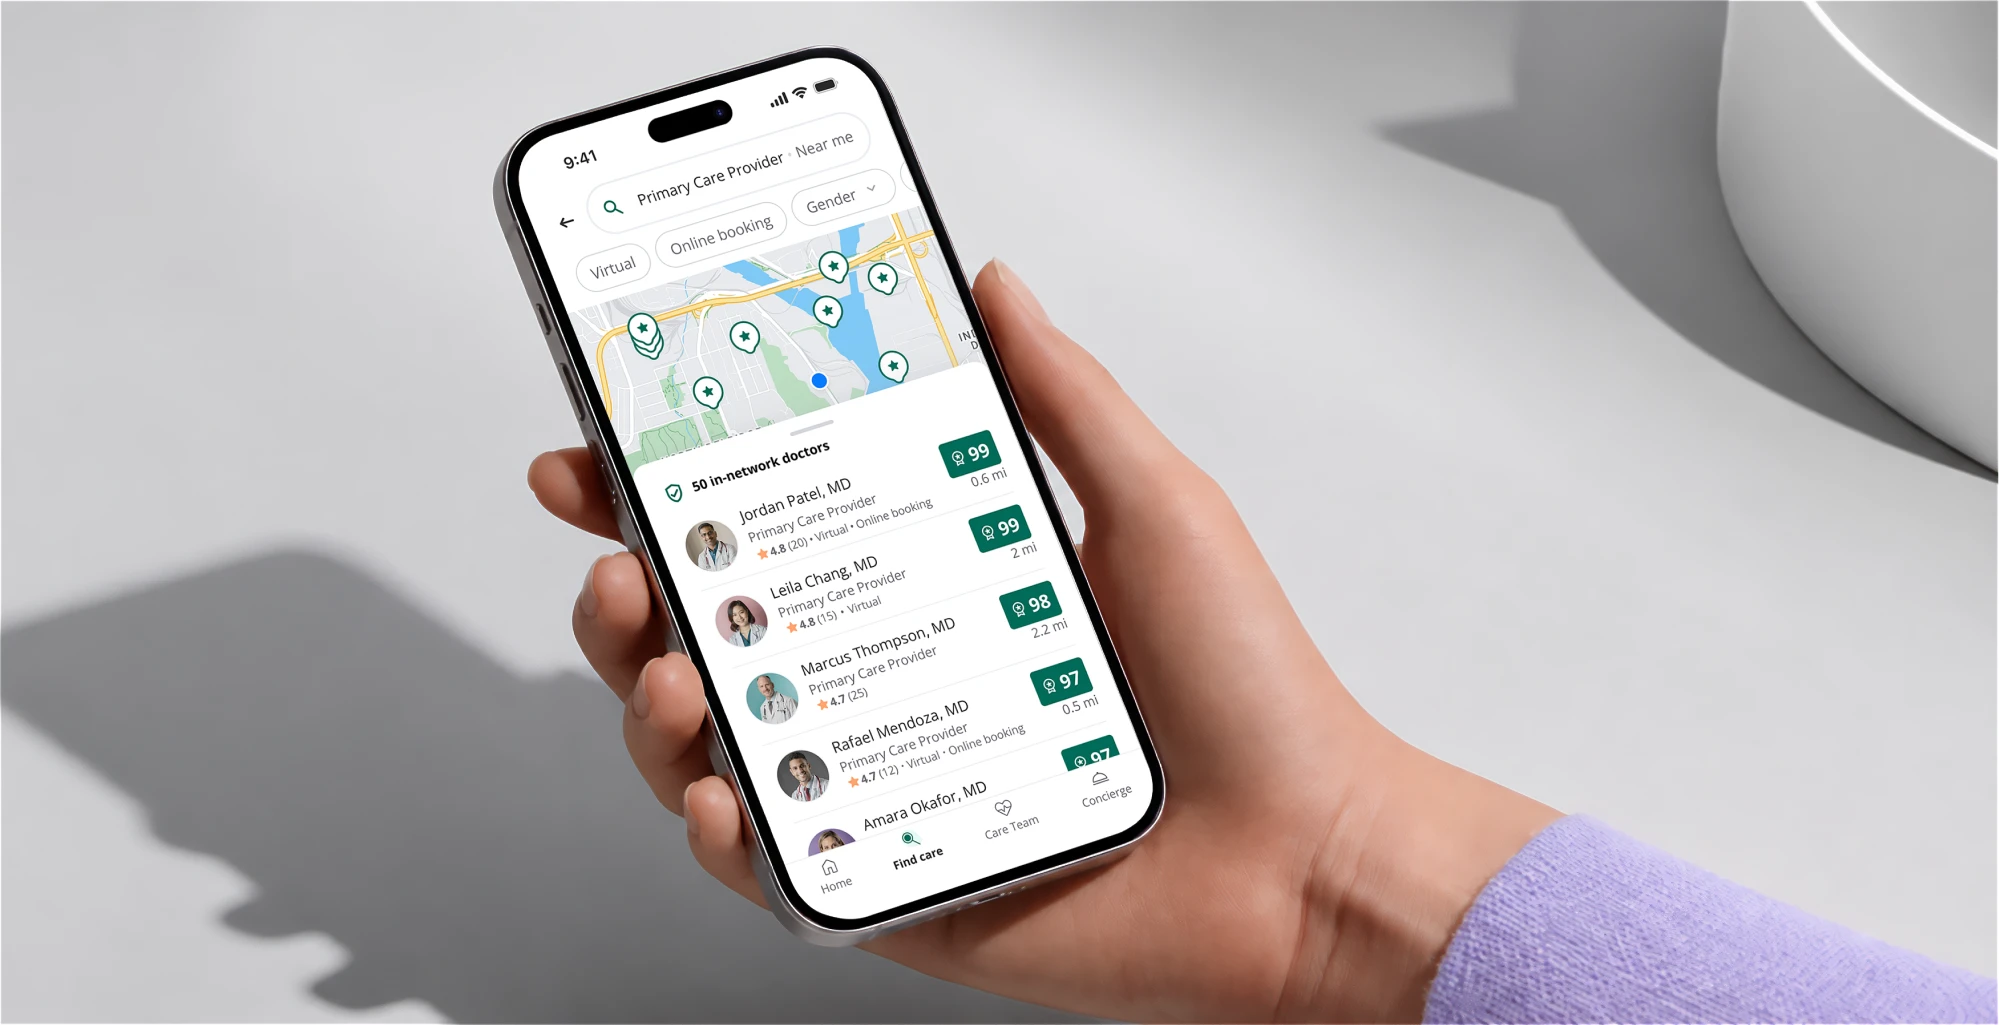
Garner is a free benefit that allows you to earn HSA contributions OR reimbursements (depending on your medical plan) for seeing the top doctors in your network. Doctor rankings are based on real patient outcomes, using one of the nation’s largest medical databases and revolutionary analytics.
Have a question?
Find answers to the most commonly asked questions from our members and learn more about your Garner benefit.
Our aim is to help you navigate your benefits with ease and confidence, ensuring your Garner experience is even more rewarding.
Download our app
There is no need to scramble to find a doctor. By downloading the Garner App, you can find Garner Top Providers, ask the Concierge for support and learn more about your Garner plan all in one place.


Frequently asked questions
Below, you’ll find answers to the most common questions you may have about your Garner benefit. If you still can’t find the answer you are looking for, contact us!
About Garner
Is Garner my health insurance?
No. Garner is not your health insurance. Garner is a separate benefit that is paired with your health insurance plan to help you find the best providers. By visiting Top Providers, you can earn contributions to your HSA or reimbursements (depending on your medical plan) equivalent to your qualified out-of-pocket costs.
If I create an account, am I obligated to see Garner’s Top Providers?
No. While we encourage you to see Top Providers to ensure you are receiving the best care, you have the choice to receive care from a doctor who is not a Top Provider. However, out-of-pocket costs from these doctors will not qualify for your benefit.
Why did my organization add Garner to my plan?
Your employer cares about your health. In order to help you find the best care, they pay for you to have the Garner benefit. High-quality care lowers costs; patients who see Top Providers will generally pay less in the long run and be healthier. For example, if you have a smooth recovery, your total cost of care will be lower than if you have complications and need to be hospitalized.
Garner helps your employer pass these savings along to you through HSA contributions or reimbursements (depending on your medical plan) for seeing the Top Providers in your network. Your Garner benefit is funded entirely by your employer or health plan sponsor.
Can my family use my Garner benefit?
Garner covers anyone in your family who is covered by your health plan. Your family only needs one account. However, any dependent over the age of 18 is welcome to create their own account. HSA contributions will only go to the primary member who holds the health insurance plan.
You can log in to your Garner account and view more details here.
How do I use the app in Spanish?
To use the app in Spanish, log into your Garner account and click here to navigate to your account settings. Under the “Language” section, choose “Spanish” from the drop-down menu.
Finding Top Providers
What is a Top Provider?
Garner identifies Top Providers by analyzing one of the largest medical claims databases in the U.S.—that’s more than 60 billion medical claims representing more than 320 million patients. They are highlighted in the Garner Health app with a green Top Provider badge and represent the best available doctors near you who are in your network and have appointment availability.
Are Top Providers in-network with my health insurance plan?
We try our best to recommend Top Providers that are in-network with your health insurance plan. Since insurance companies change their networks regularly, we always recommend verifying with your health plan that a provider is still in-network on or before the day of service.
How do I find and add Top Providers to my Care Team?
In the Garner Health app, you can search for doctors by symptom, name, or ZIP code. Look for the Top Provider badge—only doctors with this badge are eligible for your Garner benefit.
How to Add a Doctor to Your Care Team:
Click "Find Care" in the navigation bar.
Use the search bar to enter a doctor's name, specialty, condition, or procedure, then click "Find Providers."
In the search results, select a doctor with the green Top Provider badge to view their profile.
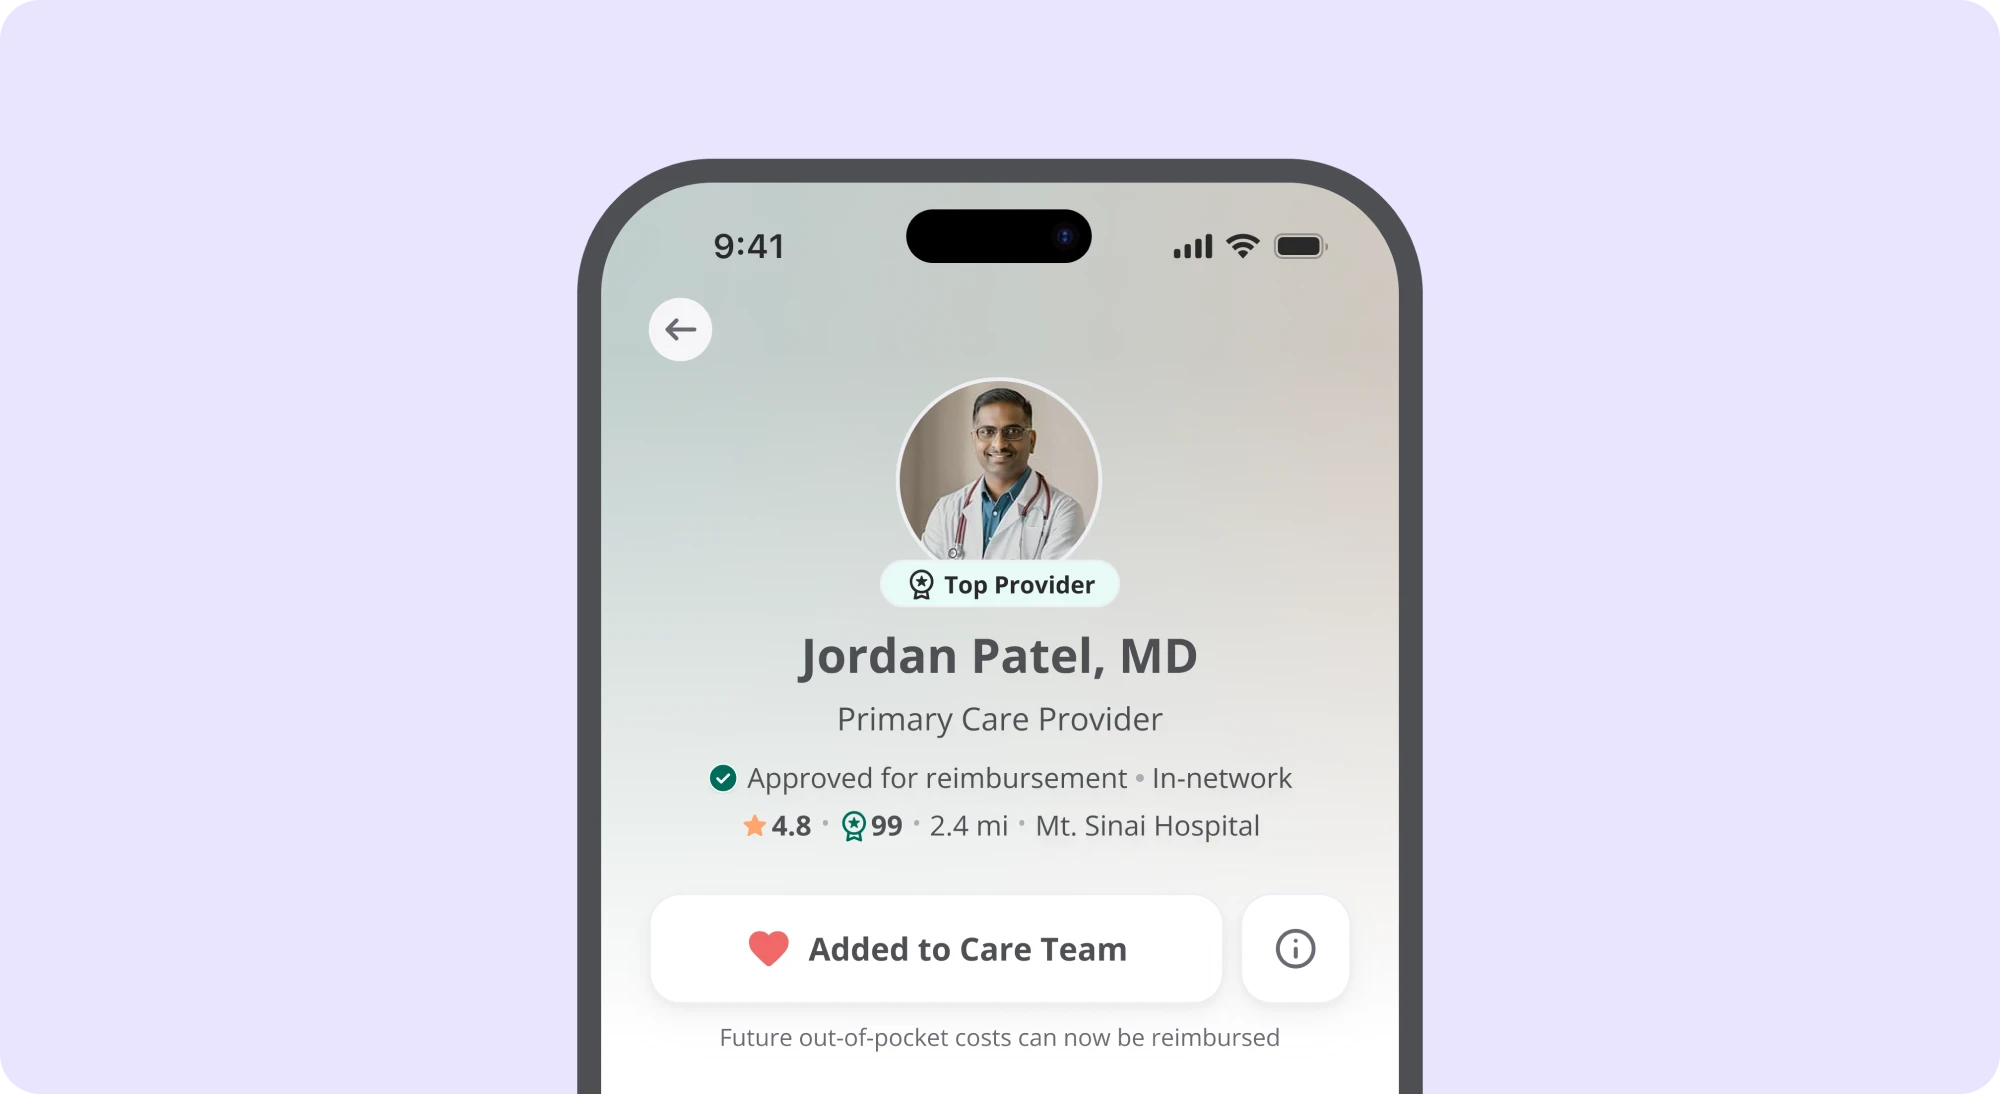
Click "Add to Care Team." A red heart will fill in to confirm the doctor has been successfully added. Your list of doctors on your Care Team will carry over each year.
This ensures the doctor is approved for your benefit and easy to find later. You can access your full Care Team from the navigation bar.
Upon request, the Concierge can also assist with adding doctors to your Care Team.
Please note: To be eligible for reimbursement of out-of-pocket costs, the doctor must be a Top Provider and in-network, and the services must be covered by your health insurance.
Can a Nurse Practitioner, Physician’s Assistant, or midwife be a Top Provider?
Yes, in primary care, psychiatry, dermatology, obstetrics, and gynecology. Garner’s methodology is unchanged: Advanced Practice Providers go through the same quality evaluation as physicians and have to clear the same Top Provider bar. Search for a Nurse Practitioner, Physician’s Assistant, or midwife in the Garner app by specialty or name.
Where can I view my Care Team?
To view your Care Team, please log into your Garner account and select "Care Team" from the navigation bar.
Do I need to add my doctors to my Care Team every year?
No. Your list of doctors on your Care Team will carry over each year.
Do I need to add a provider to my Care Team in order to be reimbursed or earn HSA contributions?
Adding a provider to your Care Team is the best way to ensure you will be reimbursed or earn HSA contributions.
Once an in-network Top Provider is added to your Care Team, they're approved for your Garner benefit, and your out-of-pocket costs for that provider qualify for reimbursement or HSA contributions.
What happens if I forget to add a provider to my Care Team?
Please add the provider to your Care Team as soon as you remember.
If Garner sees that you forgot to add a provider before your visit, we will check our records to see if you received a recommendation for that provider in the app prior to your visit date. If you did, we will still provide reimbursement or HSA contributions.
For future visits, please make sure to add a Top Provider to your Care Team before the visit. This is the best way to get reimbursed or earn HSA contributions.
What about providers I have been reimbursed or earned HSA contributions for in the past who are not on my Care Team? Do I need to add them to my Care Team?
You are welcome to, but it is not necessary. Garner will move any provider you have been reimbursed or earned HSA contributions for onto your Care Team in January 2027.
You will continue to receive reimbursements or earn HSA contributions for any providers you have been paid back for in the past.
Do the Garner Top Provider rankings ever change?
Garner Top Provider rankings can change each month. While a doctor’s quality of care typically doesn't change much month to month, this is to ensure we have the most up-to-date directory information and new patient availability.
If a member has previously added a Garner Top Provider to their Care Team, any recommendation updates will not affect the doctor’s approved status for that individual member and their dependents.
Are all providers at the same practice, medical center or physician group approved for the Garner benefit?
No. Garner evaluates the performance of individual doctors, not entire medical centers or hospitals. Use the Garner Health app to search for specific providers by name to see if they are a Top Provider and approved for your Garner benefit.
What if a colleague recommends a Top Provider they found through Garner? Do I still need to add that provider to my Care Team?
Yes. Even if your colleague found the Top Provider through Garner, search for that provider in the Garner Health app and add them to your Care Team before your visit.
How do I know if a specialist is eligible for my Garner benefit?
All providers, including specialists, must be Top Providers in order to qualify for the Garner benefit. This applies to a specialist you have already seen or a new provider. Search for a specialist by entering their name or specialty and zip code. If your specialist has a Top Provider badge, qualifying out-of-pocket medical costs from services performed or ordered by that specialist are approved for HSA contributions or reimbursement if they are added to your Care Team before your appointment.
For example, if your primary care doctor recommends seeing a GI specialist for stomach pain:
Search in the Garner Health app to confirm the specialist is a Top Provider.
If they are a Top Provider, be sure to add them to your Care Team before your appointment.
If your specialist is not a Top Provider, you can still choose to receive care from them, but the out-of-pocket medical costs will not qualify for HSA contributions or reimbursement.
Why isn't my current doctor covered by Garner?
We understand it can be disappointing if your current doctor isn't covered by Garner. Our mission is to help you access high-quality care while reducing your out-of-pocket costs.
How does Garner select Top Providers?
Garner's doctor recommendations are based on real patient outcomes to help you find the best doctors near you. Our recommendations go far beyond patient reviews. We look at billions of claims to understand the specifics of how doctors provide care.
Doctors can't pay to show up in our recommendations. Garner is an objective third party that selects Garner Top Providers based on doctors who:
Follow current medical guidelines
Avoid unnecessary procedures
Charge fair prices for their services
Help patients recover faster
Garner Top Providers are the best doctors in each specialty and region of the country. Garner always looks for the best doctor option in your region, and accounts for the number of doctors available in your neighborhood.
How does Garner evaluate doctors? We assess each doctor based on specific metrics related to their specialties, such as:
Complication rate: Measure a doctor's complication rates
Invasive procedure rate: Determine if a doctor performs more invasive procedures only when necessary given they entail longer recovery times and complication risks
Follows current medical guidelines: Evaluate if a doctor recommends optimal treatment according to medical guidelines
If your doctor isn't listed as a Top Provider, it doesn't mean they aren't a good provider—it simply means they haven't met Garner's criteria at this time. If you choose to continue seeing your current doctor, we respect your decision. However, please note that visits with non-Top Providers are not eligible for your Garner benefit.
We encourage you to consider a free second opinion from a Garner Top Provider to ensure you're receiving the best possible care. You can always return to the Garner Health app to search for new doctors for future care.
If you're currently seeing a provider for a critical or ongoing care need, please reach out to Garner Concierge through the Garner Health app or email us at concierge@getgarner.com.
What if I see a different provider in my provider's hospital or practice?
Applies to oncology, transplant, and obstetrics care only: We understand when it comes to oncologic care/transplant procedures/pregnancy, you are often asked to see multiple providers and do not have control over who will be available throughout your journey. So long as your main medical oncologist/transplant surgeon or physician/OB has been added to your Care Team before your appointments, qualifying out-of-pocket costs for related services will qualify for your Garner benefit even if your main provider is not there.
Applies to primary care, pediatrics, and gynecology care only: If you see a Top Provider at a practice that is already on your Care Team, then upon request, Garner will add other providers in that practice to your Care Team if you cannot choose your provider and need to schedule with the soonest available provider.
Qualifying Costs
What qualifying costs will be covered by my Garner benefit?
Garner provides HSA contributions or reimbursements (depending on your medical plan) for qualifying out-of-pocket medical costs for office visits, lab work, imaging and procedures. To learn if other medical costs qualify for your Garner benefit, log into your Garner account and navigate to the benefit section.
Note that whether you receive HSA contributions or reimbursements is dependent on the medical plan you enroll in.
Your out-of-pocket medical costs will qualify for your Garner benefit if:
You have created a Garner account
Your provider is in-network and the cost was covered by your health insurance plan.
The type of cost qualifies under your Garner plan.
You haven't reached your maximum annual Garner benefit.
Additionally, make sure to add the provider to your Care Team before the date of service.
When are services from facilities such as labs and imaging eligible for my benefit?
When a Top Provider orders lab work or imaging, the associated out-of-pocket costs automatically qualify for your Garner benefit if:
You added the Top Provider to your Care Team before the date of service. This is the best way to ensure you will be reimbursed or earn HSA contributions.
The facility is in-network, and the services are covered by your health insurance plan.
In this case, you do not need to search for the facility in the Garner Health app.
If you choose to find a facility yourself, you can also search for labs and imaging centers in the Garner Health app or website. To qualify for HSA contributions or reimbursements, the following conditions must be met:
You found the facility in the Garner Health app or website before your appointment.
The facility's profile page shows a yellow banner that says: "Eligible with some exceptions." This means services at the facility may qualify for your benefit.
The facility is in-network, and the services are covered by your health insurance.
Note: Garner strives to recommend in-network facilities, but insurance networks can change. Always confirm with the facility before your appointment. Garner does not recommend specific hospitals or facilities beyond those that meet the qualifications above. If you plan to use a facility that is not listed, ensure the provider ordering your care is a Top Provider and is added to your Care Team before your appointment to remain eligible for HSA contributions or reimbursements (depending on your medical plan).
Can I use my benefit for ancillary providers that I can't select, such as an anesthesiologist who assists with surgery?
We understand you can't choose ancillary providers such as anesthesiologists, radiologists and nurses. Your costs qualify under your Garner benefit if:
An in-network Top Provider is ordering or is primarily performing the service.
The service is in-network with your health insurance plan.
Make sure you add the Top Provider ordering the service to your Care Team before your visit.
To confirm coverage, check the list of services on your health insurance card or call the number on the card. If you have an online account with your health insurance provider, log in to your portal to confirm coverage details.
Does Garner cover out-of-pocket costs for dental and vision care?
Garner works with your medical insurance, which generally does not cover dental or vision services. Garner may allow you to earn HSA contributions or reimbursements (depending on your medical plan) for procedures such as oral surgery, but only if the claim for that service is processed by your medical insurance plan.
If I don’t use my health insurance plan to pay for procedures, can I still use my Garner benefit?
No. HSA contributions or reimbursements from Garner occur after costs are processed by your health insurance plan. Your health insurance plan must cover qualifying medical care and you must submit your out-of-pocket expenses to your insurance company for them to be eligible.
HSA Contribution or Reimbursement Process
How do I determine if I will receive HSA contributions or reimbursements?
Your employer offers several health plans, and the plan you choose determines whether you receive HSA contributions or reimbursement payments.
If you enroll in a health plan that includes an HSA, you will receive contributions directly to your HSA account.
If you enroll in a plan that does not include an HSA, you will receive reimbursements, either by direct deposit to your bank account or by check.
For more information, visit your benefits page in the Garner Health app or contact the Garner Concierge team.
How will my benefit arrive?
For members enrolled in an HSA contribution-eligible plan: When you visit a Top Provider, Garner facilitates an employer contribution to your HSA equal to your qualified out-of-pocket costs. Behind the scenes, we work with your employer and HSA provider to make sure these contributions are included with your other contributions on your tax forms.
For members enrolled in a Garner reimbursement-eligible plan: You have two options for receiving reimbursement:
If you are the primary member, you can set up direct deposit for faster and more secure reimbursement. You will receive your reimbursement directly to your bank account and faster than a check. Watch this demo video to learn how to set up direct deposit.
If you do not set up direct deposit, a reimbursement check in a white envelope will be sent to the mailing address the primary member has on file with their employer.
What if I have a question about a claim?
You can reach out to the Garner Concierge for answers to your questions by messaging them.
What if I have questions about a claim or what costs qualify for my Garner benefit?
To learn more about what medical costs qualify for your Garner benefit, log in to your Garner account and check your coverage details or message the Concierge for questions about a claim.
What do I need to do to earn money back from my Garner benefit?
Most of the time, you don't need to do anything—HSA contributions or reimbursements are automatic! However, if you have a medical claim over $2,000 or, if your Garner plan has prescription coverage, a prescription claim over $500, you'll get a notification in the Garner app, and the claim will show "more info needed" in the Claims section of the app. Open the claim and tap the button in the banner, then:
Enter the amount you paid out of pocket for that visit or prescription.
Add a document that shows the amount, if we need one. For a medical claim, any of these works:
An Explanation of Benefits from your health plan
A bill from your provider showing what you owe
A receipt showing what you paid
A credit card or bank statement showing the payment
For a prescription, use a pharmacy receipt showing the prescription and what you paid, or a card or bank statement showing the payment.
Submit. We'll review it and update the claim in the app.
A few things worth knowing:
If you did not pay anything, or you paid with HSA funds, enter $0.
For prescriptions under $100, entering the amount is usually all we need—no document required.
This helps ensure security and accuracy for larger payments.
How do HSA contributions affect my taxes?
All contributions facilitated by Garner are considered employer contributions.
To help you file your taxes correctly, Garner works with your employer and HSA provider to ensure Garner contributions appear in your tax documents (like your W-2 and 5498-SA) just like any other HSA contribution. You do not need a separate form from Garner to file your taxes.
Because Garner can't provide tax advice, we recommend seeking input from a tax professional about your specific tax situation.
How is the HSA contribution limit set by the IRS different from my maximum Garner benefit?
Think about your total yearly HSA contributions in two parts: the amount Garner facilitates and the amount you and your employer can contribute outside of Garner.
The maximum Garner benefit refers to how much Garner can facilitate in a year. The IRS limit is on total yearly contributions from all sources. Here’s how the two limits work together:
1. Garner’s maximum benefit
This is the most Garner can facilitate in HSA contributions during the year. It will be less than the total yearly HSA limit from the IRS.
2. IRS total HSA contribution limit
This is the total the IRS allows to be added to your HSA per year from all sources combined.
Your employer factors in Garner contributions when setting your HSA funding, but it’s ultimately your responsibility to make sure total contributions stay within IRS limits. If you go over the limit, reach out to your HSA provider or a tax advisor to understand next steps and avoid penalties.
Why was my HSA contribution limit lowered?
If your health plan is paired with an HSA, your total yearly HSA contributions come from two sources:
Your Garner benefit: When you visit a Top Provider, Garner facilitates an employer contribution to your HSA equal to your qualified out-of-pocket costs within 6-8 weeks.
Your personal & employer contributions: The money you contribute from your paycheck, plus any amount your employer adds to your HSA.
Your employer lowered your HSA contribution limit to leave room for your Garner benefit, so your total contributions from all combined sources stay within the IRS limit.
Can I contribute more to my HSA if I don't use my full Garner benefit?
Yes. If you are enrolled in an HSA-eligible medical plan, and if you don’t use your full Garner benefit, you can contribute more to your HSA—up to the IRS limit.
Here’s how the deadlines generally work for a given tax year:
Garner's contributions:
Garner will facilitate the last HSA contribution for the year by December 31.
Your personal and employer contributions:
Can be made until the tax deadline on April 15 of the following year.
Do I need to use my HSA card to qualify for HSA contributions?
No. If you are enrolled in an HSA-eligible medical plan, regardless of how you pay, you will receive an equivalent contribution directly to your HSA. If you pay for an eligible expense with your credit card, debit card or bank account, you can use your HSA funds to pay yourself back.
My claim was denied. How do I ask Garner to take another look?
There are several reasons why a claim might not qualify for your Garner benefit; for example, your provider may not be a Top Provider, or the services may be out-of-network according to your insurance. If you believe your claim was denied in error, you can request a review right in the app:
Open the denied claim in your Claims list.
Tap the option to request a review.
Tell us why you think it should be covered. Depending on the denial reason, we may ask you to pick the Top Provider you saw.
Upload a document if we ask for one. This is usually required for claims of $100 or more—an Explanation of Benefits, a bill, or a receipt showing the service.
Add a note if there's anything else we should know, then submit.
Your claim will show as in review, and you can see the documents and notes you sent from the claim itself. We'll send you a notification once it's been reviewed. The Concierge team may reach out to you for more information.
A claim is missing from my Garner Health app. What should I do?
Claims come to us from your health plan, and they can take up to 8 weeks after your visit to appear. If it's been less than that, the claim is most likely still on its way—check back once 8 weeks have passed.
If more than 8 weeks have gone by and you still don't see it, you can submit it yourself in the app. Go to the Concierge tab and let us know your claim is missing. We'll ask for the date of your visit, show you what we already have for that date, and if the claim really is missing, walk you through submitting it.
How do I submit a missing claim?
Once you've confirmed the claim isn't in your app, you'll be asked for:
The amount you paid out of pocket
The name of the provider you saw
A document from your health plan—an Explanation of Benefits (EOB) for a medical visit or, if your Garner plan has prescription coverage, a prescription slip for a pharmacy claim
Any notes you think we should know
Then submit. You'll see the claim marked as under review in your Claims list, and we'll update you once it's been reviewed.
I saw an approved Nurse Practitioner, Physician’s Assistant, or midwife and I have not received my reimbursement or HSA contribution yet. What happened?
About 20% of the time, a claim for an Advanced Practice Provider reaches us under the supervising physician's name rather than your provider's. When this happens, we can’t match the claim to a provider on your Care Team automatically. If this happens, please reach out to Concierge so we can link the providers together and reprocess your claims.
HSA and FSA Process
What if I have an FSA?
If you have a health FSA, special rules apply to your Garner benefit. You may not earn HSA contributions or get reimbursements through Garner for an out-of-pocket medical cost that will also be paid using your FSA. This is often referred to as double-dipping and is prohibited by the IRS. If your Garner benefit and your FSA cover the same medical cost, we recommend you use and exhaust your Garner funds before using your FSA. You can save your FSA for when your Garner benefit has reached its limit or for out-of-pocket medical costs that don't qualify for your Garner benefit. Use your FSA to cover costs Garner can't cover, such as dental care.
Is Garner my HSA?
No. Garner is not an HSA provider and does not administer your HSA. Garner works with your employer to help inform their contributions to your HSA based on your qualified out-of-pocket medical costs.
Concierge Support
What is the Garner Concierge?
The Garner Concierge is a group of professionals dedicated to answering your questions and helping you find the best care for you and your family. If you need help finding a Top Provider or have a question about your benefit, you can message the Concierge for assistance.
How do I contact the Garner Concierge?
You can message through in-app chat in the Garner Health app, email at concierge@getgarner.com, or phone at (866) 761-9586. Concierge hours of operation are Mon-Fri 8 a.m. to 10 p.m. ET. Se habla español.
Can't find the answer you're looking for?
Our dedicated Concierge is here for you. Concierge hours of operation are Mon-Fri 8 a.m. to 10 p.m. ET. Se habla español.